Loan Payments Have Become Unmanageable
Income is no longer enough to cover ordinary living expenses while also meeting obligations to banks or other creditors.
PERSONAL BANKRUPTCY
We help determine whether bankruptcy is suitable for you and what consequences it may have for debts, property, a mortgage and family assets. If court proceedings are required, we prepare the application and handle the case in a Russian commercial court through resolution of the issue of discharge from obligations.
If your situation meets the statutory conditions for out-of-court bankruptcy through an MFC, we will tell you this before starting a paid court-bankruptcy procedure.
WHEN AN ASSESSMENT IS NEEDED
Income is no longer enough to cover ordinary living expenses while also meeting obligations to banks or other creditors.
Payments are spread among different creditors, arrears arise, and penalties and new claims accumulate.
Enforcement proceedings have been opened, funds are being withheld or restrictions imposed, and the next scenario needs to be assessed.
Before filing, it is necessary to understand what property enters the bankruptcy estate, what is protected by law and where there is a risk of realization.
The mortgage loan, the status of the residence and the possibility of preserving the sole mortgaged residence under the conditions provided by law need to be assessed separately.
It is necessary to consider not only property registered personally to the debtor, but also the debtor’s possible share in the spouses’ joint property.
The creditor’s claims, the stage of the case, property and obligations need to be reviewed and the citizen’s position in the already commenced proceedings determined.
The amount of debt and whether one of the special statutory grounds for the out-of-court procedure exists need to be checked.
Nikolay NemkovManaging Partner, Konsultant Law Firm
Managing Partner’s Commentary
Why, before filing, it is necessary to review not only the amount of debt, but also property, transactions, a mortgage, family assets and obligations that may remain even after the procedure is completed.
BEFORE FILING
Bankruptcy affects more than debt. Court proceedings affect the citizen’s property, transactions, relationships with creditors and, in some cases, the spouses’ joint property. The right question before filing is therefore not “how much debt will be written off?” but “what will happen in my specific situation?”
We identify creditors, amounts, the grounds of obligations, enforcement proceedings and the current stage of recovery.
We review real estate, vehicles, shares, bank accounts and other assets that may be relevant in the procedure.
We analyze significant transactions involving property and funds during the period that may be reviewed in the bankruptcy case.
We determine whether court bankruptcy is required or whether the situation meets the conditions for the out-of-court procedure through an MFC.
WHAT WE DO
We analyze debts, property, income, enforcement proceedings, marital status, mortgage obligations and significant transactions.
We explain which assets may be affected by the procedure, which obligations may remain and which circumstances require additional assessment.
We prepare information on creditors and debtors, property, income and other documents required for a citizen’s application to a Russian commercial court.
We prepare the application to declare the citizen bankrupt and the procedural filing package for the Russian commercial court.
We prepare the position and documents on issues arising during the case and handle the progress of the procedure.
We handle legal issues arising in work with the financial administrator, creditors, claims and the citizen’s property.
We handle the case through the court act completing the applicable procedure and resolving the issue of discharge from further performance of obligations.
TWO PROCEDURES
Court Bankruptcy
Court bankruptcy is conducted under Chapter X of the Bankruptcy Law. A financial administrator must participate in the case. Depending on the circumstances, the court applies the procedures provided by law, while property and creditors’ claims are considered within the court case.
Out-of-Court Bankruptcy
The out-of-court procedure is not available to every debtor. The law sets the amount of debt taken into account at RUB 25,000 to RUB 1,000,000 and requires at least one of the special statutory grounds connected with enforcement proceedings or the citizen’s status.
RUB 25,000–1,000,000range of debt taken into account for out-of-court bankruptcy
We first check the conditions for the free out-of-court procedure. If they are met, we do not recommend court bankruptcy simply in order to sell a legal service.
PROPERTY
Sole Residence
Property that cannot be subject to enforcement by law is excluded from the bankruptcy estate. The issue of the sole residence suitable for living is assessed in light of enforcement-immunity rules and the circumstances of the particular case.
Mortgaged Residence
The mere fact that a mortgaged apartment is the debtor’s sole residence does not create unconditional immunity from the secured creditor’s claims. At the same time, the Bankruptcy Law provides for a separate settlement agreement with the mortgage creditor which, if the statutory conditions are met, may allow the debtor to preserve the sole mortgaged residence and continue performing the mortgage obligation.
Spouses’ Joint Property
The citizen’s share in the spouses’ joint property may be relevant in the procedure. Family property and the history of its acquisition should therefore be analyzed before filing.
EXPERT COMMENTARY
Nikolay Nemkov and the experts at Konsultant Law Firm comment in the media on issues related to this practice area.
The firm has been practicing since 2007. We handle litigation and complex legal matters for businesses in Krasnoyarsk, Moscow and other regions of Russia.
After settlements with creditors are completed, the law provides for discharge of a good-faith citizen from further performance of a substantial part of the claims. But there are exceptions to this rule, and in certain cases the court may decline to apply discharge from obligations at all.
Before filing, it is therefore important to review not only whether the procedure can be commenced, but also the composition of the debt, the debtor’s good faith and the circumstances in which the obligations arose.
CLIENT TESTIMONIAL
Khamitov
Khamitov — client of Nikolay Nemkov
“Now I am debt-free and can use my bank cards normally.”
Khamitov turned to Nikolay Nemkov for assistance with a personal-bankruptcy procedure. According to the client, the procedure lasted about a year and a half.
After it was completed, the client highlights what matters most to him: the debts are gone, and he can once again use bank cards normally.
There are no complicated legal terms in this testimonial. The client describes the result of the procedure in the way he experiences it in everyday life.
For a person, the result of the procedure is not only a completed court case, but also the ability to use ordinary financial tools again without the previous debt pressure.
Debts, creditors, income, property, enforcement proceedings, mortgage obligations and marital status.
We identify assets and circumstances that may be relevant to the procedure and creditors.
Court bankruptcy, the out-of-court MFC procedure or another way of addressing the debt situation.
We assemble the documents, prepare the application and begin court support for the procedure.
MANAGING PARTNER
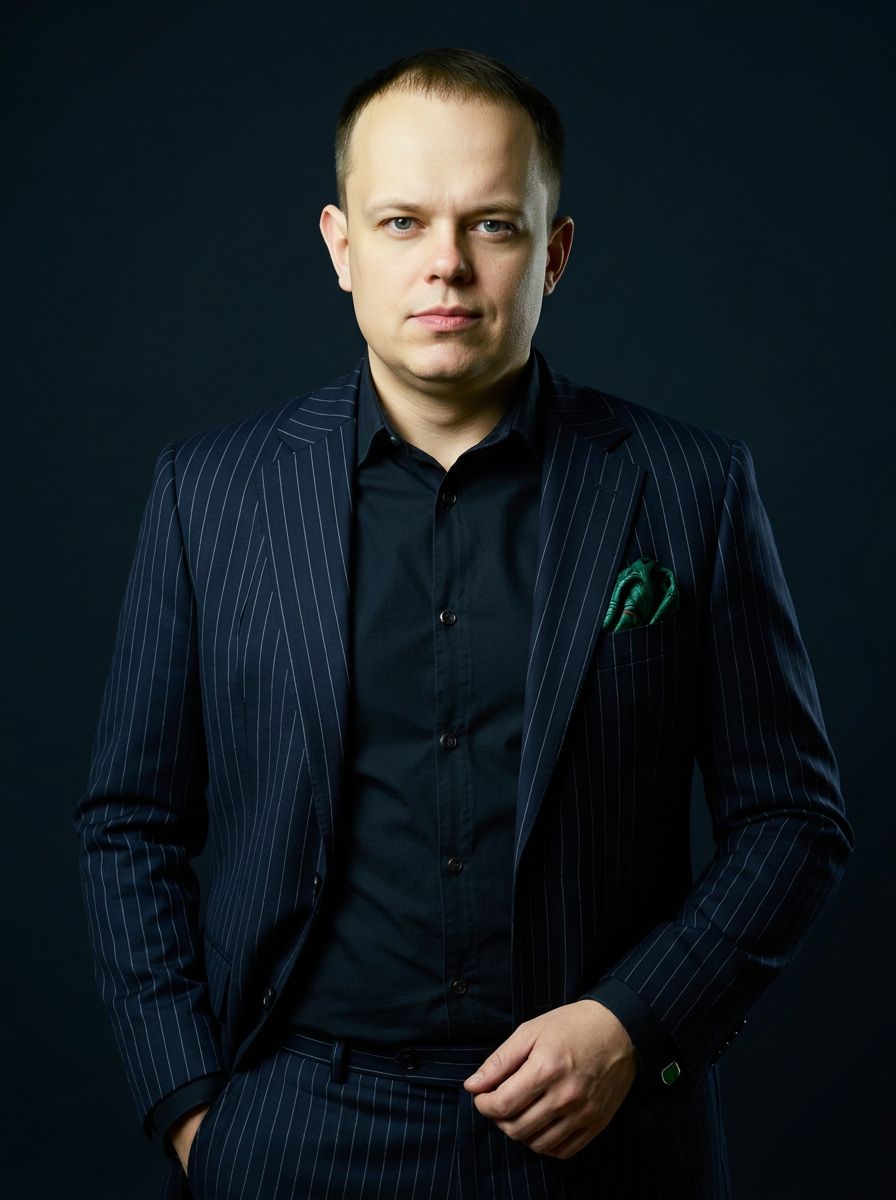
Managing Partner, Konsultant Law Firm
More than 20 years of practice in complex property and corporate disputes. Practicing insolvency practitioner.
Personal Bankruptcy in Practice
Practical answers about debt discharge, property, a debtor’s only home, out-of-court bankruptcy and the consequences of personal bankruptcy in Russia.
Personal bankruptcy may be considered when an individual is objectively unable to meet financial obligations and ordinary debt resolution methods do not solve the problem.
Before starting bankruptcy proceedings, it is important to analyse not only the amount of debt but also creditors, property, income, enforcement proceedings, previous transactions and the nature of the obligations.
Bankruptcy should not be treated as an automatic way to eliminate every debt. It is first necessary to determine whether judicial or out-of-court bankruptcy is available and what consequences the procedure may have.
As a general rule, after completion of settlements with creditors, an individual declared bankrupt is released from further performance of creditor claims, but Russian law provides important exceptions.
Claims relating to current payments, child support, compensation for harm to life or health, salary and severance payments, compensation for moral harm and other claims inseparably connected with the creditor’s personality remain in force. The law also contains special exceptions for certain claims, including subsidiary liability and some claims for damages.
In addition, a court may refuse to release the debtor from obligations where dishonest or unlawful conduct established by law is proven. Before bankruptcy, it is therefore necessary to determine which particular obligations may actually be discharged.
Legal basis: Article 213.28 of Federal Law No. 127-FZ.
When the asset realization procedure is introduced, property owned by the debtor on the date of bankruptcy, as well as property subsequently identified or acquired within the limits established by law, generally forms the bankruptcy estate, except for property protected from enforcement by law.
Before bankruptcy, real estate, vehicles, ownership interests, funds and other assets should therefore be analysed separately, together with any applicable exemptions.
Where property is jointly owned by spouses, bankruptcy may also affect the debtor’s share in that common property. Russian law provides mechanisms intended to protect the property interests of the non-bankrupt spouse when common property is sold.
Legal basis: Articles 213.25 and 213.26 of Federal Law No. 127-FZ.
It is important to distinguish between a debtor’s only residence suitable for permanent living and a residence that is subject to a mortgage.
In circumstances established by law, a debtor’s only suitable residence may be protected by enforcement immunity. However, mortgaged property is subject to a special legal regime, and the fact that a mortgaged apartment is the debtor’s only home does not automatically prevent its realization.
Since 2026, Russian bankruptcy law separately regulates distribution of proceeds from the realization of a debtor’s only residence where that property is mortgaged. Mortgaged real estate should therefore be analysed separately before filing for bankruptcy.
Legal basis: Articles 213.25 and 213.27-1 of Federal Law No. 127-FZ and Article 446 of the Russian Civil Procedure Code.
Yes. Federal Law No. 127-FZ provides an out-of-court personal bankruptcy procedure through a multifunctional public services center where the statutory conditions are met.
As of September 2026, the total amount of monetary obligations and mandatory payments counted for this procedure must be at least RUB 25,000 and no more than RUB 1,000,000.
The debt amount alone is not sufficient. The individual must also meet at least one of the grounds expressly provided by Article 223.2 of the Bankruptcy Law. Eligibility should therefore be assessed based on the individual circumstances and status of enforcement proceedings.
Legal basis: Article 223.2 of Federal Law No. 127-FZ.
Personal bankruptcy may release an individual from certain debts but also creates statutory consequences.
For five years after completion of the asset realization procedure or termination of the bankruptcy case during that procedure, an individual taking a loan or credit must disclose the fact of bankruptcy. During the same period, restrictions apply to starting another bankruptcy case on the individual’s own application.
Russian law also imposes restrictions on participation in management of legal entities: generally three years, with longer special periods for certain financial organizations. These consequences should be considered before starting bankruptcy proceedings.
Legal basis: Article 213.30 of Federal Law No. 127-FZ.
Yes. The right to apply to a Russian arbitrazh court for an individual to be declared bankrupt belongs not only to the individual but also to a bankruptcy creditor and an authorized state body.
As a general rule, an application for an individual’s bankruptcy is accepted where the claims amount to at least RUB 500,000 and have remained unpaid for three months after they became due, unless the Bankruptcy Law provides otherwise.
Where bankruptcy is initiated by a creditor, the debtor should assess not only the amount of debt but also property, previous transactions, evidence and possible consequences of the procedure.
Legal basis: Article 213.3 of Federal Law No. 127-FZ.
State the approximate amount of debt, whether enforcement proceedings have been opened, what property is registered in your name and whether you have a mortgage. Before proposing a court procedure, we will first assess its consequences and whether out-of-court bankruptcy through an MFC is available.