An Account or Assets Were Blocked on a Platform
The service rules, reasons for the restriction, transaction history, review procedure and available claim mechanisms need to be assessed.
DIGITAL ASSETS
Was an account or transfer blocked, did a crypto transaction lead to a dispute, is a bank asking about the source of funds, do you need to prove ownership of digital currency or address tax issues? We first reconstruct the factual chain of operations and determine which documents and digital data can support your position.
We handle disputes involving cryptocurrency and other digital assets, P2P operations, account restrictions, bank compliance, taxation, mining and the legal architecture of digital projects.
WHAT HAPPENED?
The same transaction may be part of a purchase, investment, settlement between individuals, fraudulent scheme or evidence of the source of funds. The legal structure depends on the facts.
The service rules, reasons for the restriction, transaction history, review procedure and available claim mechanisms need to be assessed.
The parties’ agreement, transfer of the digital asset and the content of the other party’s obligation need to be proven.
Questions arose regarding incoming funds after P2P operations, sale of digital currency or transfers between participants in a transaction.
We first preserve transactions, addresses, correspondence and the circumstances of access to the assets, and then determine the possible legal protection routes.
The acquisition, sale or other disposal of digital currency needs to be reconstructed and the documents supporting income and expenses identified.
The legal model of the product, user relationships, handling of digital assets and regulatory restrictions need to be determined.
Nikolay NemkovManaging Partner, Konsultant Law Firm
NIKOLAY NEMKOV ON CRYPTO DISPUTES
A network record may show movement of a digital asset between addresses, but by itself it does not always answer who controlled the addresses, why the transaction took place, what the parties agreed and whether the counter-obligation was performed.
LOGIC OF A CRYPTO DISPUTE
In an ordinary dispute, the parties often begin with a written agreement. In a crypto dispute, there may be no agreement in the usual form: arrangements remain in a messenger, money moves through a bank, the digital asset moves through a blockchain, and part of the operation may occur on a foreign platform. The entire chain must therefore first be assembled into one factual picture.
Purchase, sale, exchange, investment, transfer of funds into management, payment or another economic purpose.
Which bank payments and blockchain transactions were made, to which addresses and in what sequence.
We review available information about the counterparty, account holders, payment details and services used.
A formal claim, platform dispute, demand against a counterparty, application to public authorities, court proceedings or another legal route.
A transaction hash confirms an operation on the network. But to turn it into legal evidence, the transaction must be connected to specific persons and a specific obligation.
WHAT WE DO
We reconstruct the parties’ arrangements, bank payments, movement of digital assets and actual conduct.
We review transactions, wallet addresses, transaction history, correspondence, platform documents and other available information.
We determine the legal nature of the relationship and formulate claims where an arrangement was not performed.
We analyze the reason for the restriction, platform rules and the available review procedure.
We help structure an explanation of the economic purpose of operations and documents supporting the source of funds.
We determine which operations need to be accounted for and which documents support acquisition, disposal, income and expenses.
We analyze the product’s legal model, user relationships, documents and regulatory restrictions.
We build the evidentiary and legal position where the conflict requires court protection.
DO NOT MIX THE CONCEPTS
In everyday language, different digital instruments are often described with the single word “crypto.” That is insufficient for legal analysis. Russian legislation regulates digital currency and digital financial assets separately, and the legal regime of a particular instrument depends on how it is structured and issued.
A separate regulated object subject to specific rules on circulation, taxation and mining.
Digital rights issued and circulated within infrastructure provided for by Russian legislation.
Legal classification depends on the structure of the instrument itself and the relationships between its holder, issuer and platform.
Legal assessment depends on what right or economic interest is actually represented by the digital record.
Before preparing a legal opinion, we first determine exactly which type of digital object is involved.
DIGITAL TRACE
Public network data can show certain parameters of a transaction, but in court or a banking dispute it is usually also necessary to connect a blockchain address to a specific person and explain the economic purpose of the operation.
Identifies a specific operation on the relevant network.
We record sender and recipient addresses and their role in the chain of operations.
Transaction history, profile data and other information may connect a user with specific actions.
May support the fiat part of the transaction and the relationship between its participants.
Shows the subject of the agreement, price, payment details and subsequent conduct of the parties.
Agreements, receipts, exports, applications, service responses and documents on the source of assets.
A wallet screenshot may be useful, but the evidentiary position should not be built on a single screenshot.
P2P
In P2P operations, bank-money movement and movement of digital currency take place in different systems. Additional risk arises when the payer, recipient of the digital asset and account holder are different persons.
For analysis, we reconstruct:
A P2P dispute cannot be analyzed solely from a bank statement or solely from the blockchain. The two parts of the operation must be connected.
ACCESS TO ASSETS
Crypto platforms may apply procedures for reviewing users, source of funds and particular transactions. The specific procedure depends on the service rules, jurisdiction and circumstances of the operation.
Save notices, support messages and account status.
Determine which action or transaction led to additional review.
Prepare documents on the source of assets and the economic purpose of operations.
Prepare the request in line with the particular service requirements and available evidence.
We do not promise to “unblock any exchange.” The platform’s legal status, rules and basis of the restriction must first be understood.
ASSETS ARE GONE
Where a wallet is compromised, fraud occurs, an investment scheme is used or assets are transferred to a fraudster, it is important to preserve addresses, transactions, messages and participant data as early as possible.
The original address or account and the circumstances of access.
Destination addresses and the subsequent traceable chain of transactions.
Phishing, disclosure of a seed phrase, remote access, investment scheme, false transaction or another scenario.
Accounts, phone numbers, bank details, correspondence and other identifiers.
Requests to support, the bank, law-enforcement authorities or other organizations.
Technical traceability of a transaction and the legal ability to recover the asset are not the same thing. The prospects depend on whether the participants can be identified and a real legal mechanism applied to them.
CRYPTOCURRENCY → RUBLES
Regular incoming payments from different individuals, P2P operations and subsequent movement of funds may raise questions from a bank. In such a situation, the source of the digital assets, transactions through which they were sold and the connection between bank receipts and specific operations need to be reconstructed.
Depending on the situation, the explanation package may include:
There is no single universal “cryptocurrency letter” suitable for every bank and every transaction.
TAX HISTORY OF THE ASSET
Russian tax legislation establishes specific rules for operations with digital currency. Where there is a significant volume of operations, documents allowing income, expenses and the tax base to be determined should therefore be reconstructed in advance.
Purchase, mining, receipt through another operation or another documented basis.
We identify available documents on the original cost.
Sale, exchange, transfer or another operation.
Statements, platform history, bank operations and other evidence.
The statement “I bought this cryptocurrency several years ago” does not by itself prove tax expenses. The documented acquisition history has independent significance.
CRYPTOCURRENCY AS THE RESULT OF ACTIVITY
Digital-currency mining is regulated separately from ordinary purchase and sale of cryptocurrency. The legal assessment depends on the status of the person, the applicable tax regime, compliance with requirements governing the activity and proper documentation of the digital currency received.
An individual, individual entrepreneur or organization.
Own equipment, infrastructure or participation in another organizational model.
Receipt of digital currency and subsequent operations need to be documented.
Sale or another disposal creates separate documentation and taxation issues.
Do not automatically apply the rules of ordinary cryptocurrency trading to mining — these are different tax and legal situations.
IMPORTANT FOR BUSINESS
Russian legislation places restrictions on using digital currency as consideration for goods, work and services. A business model therefore cannot be built on the principle “we simply accept cryptocurrency instead of rubles” without analyzing the applicable legal regime.
Certain mechanisms may apply under special legal regimes and in foreign-trade activity, but they cannot automatically be transferred to ordinary domestic settlements in Russia.
The technical ability to accept cryptocurrency does not itself mean there is a legal right to use it in the chosen payment model.
BEFORE LAUNCH
Blockchain technology by itself does not determine the legal nature of a product. It is necessary to understand what the user receives: a digital asset, a claim right, access to a service, an investment instrument, an in-game object or another right.
What the project technically and economically creates.
Which rights the person receives after payment or connection.
Where funds come from and which counter-obligations arise.
User Agreement, Privacy Policy, agreements and other documents must correspond to the actual product model.
Public promises must not contradict the legal structure of the project.
We assess whether Russian and, where necessary, foreign regulation applies.
A White Paper does not replace an agreement and does not by itself resolve the legal classification of the project.
CODE AND LAW
A smart contract may automate performance of certain conditions, but a dispute can still arise over the content of the agreement, an error in the code, authority of participants or whether the actual result corresponds to the agreed terms.
The legal analysis must therefore be carried out together with the technical logic, but not replaced by it.
“The code executed” and “the obligation was properly performed” are not always the same conclusion.
DIGITAL INHERITANCE
After the owner of digital assets dies, heirs may face both a legal question concerning the composition of the estate and a technical question concerning access to the wallet or account.
The deceased’s connection to the digital asset needs to be established.
Determine which property rights form part of the estate.
An inheritance right does not automatically provide a seed phrase or account access.
If the asset was held on a centralized service, the documents and procedure of that particular platform matter.
Inheritance of a crypto asset cannot be reduced to the question “who knows the password.”
EXPERT COMMENTARY
Nikolay Nemkov and the experts at Konsultant Law Firm comment in the media on issues related to this practice area.
The firm has been practicing since 2007. We handle litigation and complex legal matters for businesses in Krasnoyarsk, Moscow and other regions of Russia.
PRACTICAL APPROACH
The more time passes after an operation, the harder it becomes to reconstruct accounts, correspondence, bank documents and the transaction context. The original data should therefore be preserved before a formal claim or court filing is prepared.
After that, digital events are translated into ordinary legal terms: who promised what to whom, what was transferred, what was received and which obligation remains unperformed.
A crypto dispute may be technologically new, but the court still needs understandable facts, evidence and a specific claim.
HOW TO START
What happened, which digital asset was used, who the other party was and what problem arose.
We match transactions, bank operations, accounts, correspondence and documents.
We identify what relationship arose between the parties and which protection route is available.
We prepare applications, a formal claim, a position for the bank, documents for a public authority or court proceedings, depending on the situation.
MANAGING PARTNER
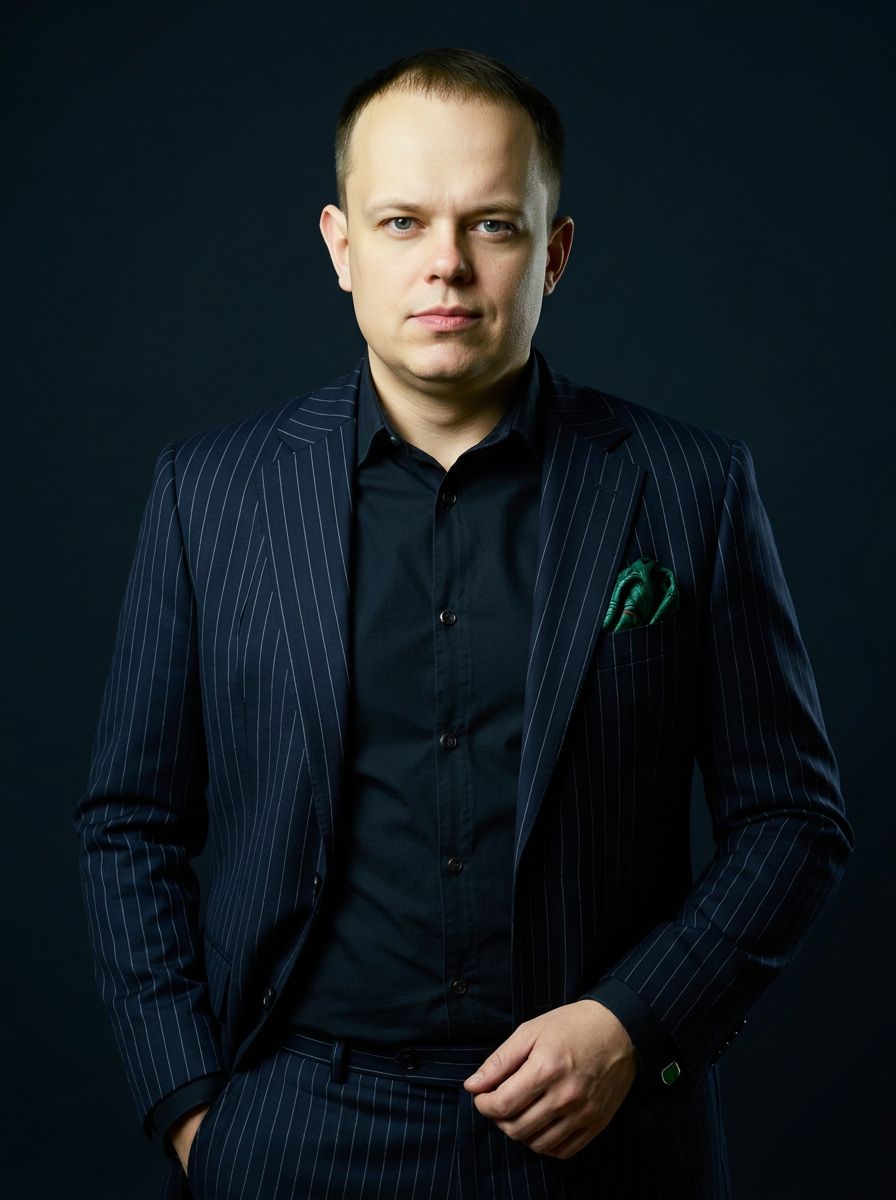
Managing Partner, Konsultant Law Firm
More than 20 years of practice in complex property and corporate disputes. Practicing insolvency practitioner.
Crypto Disputes and Digital Assets in Practice
Practical answers based on the regulation effective from September 1, 2026: digital-currency transactions, payments, P2P operations, account restrictions, evidence, taxation and mining.
From September 1, 2026, the principal special regulation of digital currencies in Russia is established by Federal Law No. 282-FZ “On Digital Currencies and Digital Rights.” The law defines digital currency as property.
Ownership of digital currency and lawful transactions involving it should be distinguished from using cryptocurrency as a means of payment. Russian law establishes specific requirements and restrictions for certain types of circulation, market participants and transactions.
Before assessing a transaction legally, it is necessary to determine whether the particular asset qualifies as digital currency under Russian law, how it was acquired, who the parties are and what purpose the transaction serves.
As a general rule, digital currency may not be accepted in Russia as a means of payment, consideration or another method of paying for goods, work, services, information or intellectual property.
Federal Law No. 282-FZ provides specific exceptions. In particular, special rules apply to the use of digital currency under foreign-trade agreements between residents and non-residents and to certain other transactions provided by law.
The technical ability to accept USDT, BTC or another digital currency therefore does not mean that a particular payment model is legally permitted. The parties, subject of the transaction, territory and legal basis of the payment must be analysed.
The first step is to determine which entity restricted access, the jurisdiction in which it operates, the platform rules that apply and the stated reason for the restriction.
Notices of the restriction, support correspondence, transaction history, account data, wallet addresses, transaction hashes and documents confirming the source of digital assets and funds should be preserved.
The appropriate protection route depends on the status of the platform and the reason for the restriction. Procedures and available remedies may differ significantly between a regulated Russian organization and a foreign crypto platform.
A blockchain record may confirm movement of digital currency between addresses, but by itself it does not always prove who controlled those addresses, why the transaction occurred or what obligation existed between the parties.
The digital trail should therefore be connected with conventional evidence such as account records, platform documents, correspondence, bank transactions, transaction terms, wallet addresses and transaction hashes.
The clearer the connection between a particular person, a particular address and the legal basis for the transfer, the easier it is to establish the factual structure of the dispute. A seed phrase or private key should not be provided to a lawyer, counterparty or support service.
When a bank asks questions, it is important to reconstruct not only the movement of money through the bank account but also the related digital-currency transaction.
Relevant evidence may include P2P order history, counterparty information, bank records, wallet addresses, transaction hashes, the acquisition history of the digital currency and documents supporting the source of funds or digital assets.
The required documents depend on the particular transactions and the bank’s questions. There is no single document that automatically removes every restriction, so the banking trail and digital trail of the same transaction should first be connected.
Digital-currency transactions have tax consequences. For an individual selling or otherwise disposing of digital currency, the income received, documented acquisition cost and transaction-related expenses are relevant within the rules of the Russian Tax Code.
As of September 2026, the Russian Federal Tax Service states that income of individuals from the purchase and sale or other disposal of digital currency is subject to personal income tax at 13 percent and 15 percent on the portion of the relevant tax base exceeding RUB 2.4 million.
It is therefore important to preserve the acquisition and disposal history, platform records, bank transactions and other documents that can support income and expenses. Separate rules apply to mining.
Yes, but digital-currency mining is regulated separately. From September 1, 2026, the principal requirements for this activity are established by Federal Law No. 282-FZ.
Russian legal entities and individual entrepreneurs may conduct mining after being entered in the relevant register. A Russian citizen who is not registered as an individual entrepreneur may mine digital currency provided that the energy consumed for this activity does not exceed the limits established by the Russian Government.
Mining also involves statutory record-keeping and information requirements, and digital currency obtained through mining is subject to a separate tax regime. Ordinary cryptocurrency purchases should therefore not be treated in the same way as digital currency obtained through mining.
CRYPTO SITUATION REVIEW
Briefly describe what happened: a transaction, P2P operation, block, counterparty dispute, bank request, tax issue or crypto-project problem. State which transactions and documents have been preserved.