The Insurer Refused Payment
The insurer argues that the event is not insured, relies on an exclusion or alleges a breach of the policy terms.
INSURANCE DISPUTES
Has the insurer refused payment, reduced the amount or argued that the event is not covered? We review the agreement, insurance rules, event documents and loss calculation. We determine what needs to be proven and which legal route should be used.
We handle disputes involving insurance of property, liability, cargo, real estate, equipment, vehicles and other types of insurance. We represent policyholders, beneficiaries and businesses across Russia.
In an insurance dispute, it is not enough simply to obtain the insurer’s refusal. The specific ground for the refusal and the documents that may rebut it need to be identified.
The insurer argues that the event is not insured, relies on an exclusion or alleges a breach of the policy terms.
The insured event was accepted, but the parties dispute repair costs, property value, restoration costs or the amount of the actual loss.
The insurer repeatedly asks for additional documents, delays consideration of the claim or makes payment dependent on formal requirements.
The cause of a fire, accident, flooding, breakdown, cargo loss or another event has become the basis for refusal or reduction of payment.
Property, equipment, real estate or cargo has been damaged, or another insured risk has arisen that may affect the company’s operations.
The legal basis, amount of the alleged loss, the insurer’s documents and causation need to be reviewed.
Nikolay NemkovManaging Partner, Konsultant Law Firm
Managing Partner’s Commentary
Before going to court, the structure of the insurance coverage needs to be understood: what risk was insured, what actually happened, which exclusions the contract contains and how the amount of loss is proven. An error at this stage can determine the outcome of the entire dispute.
INSURANCE DISPUTE LOGIC
The fact that damage occurred does not automatically mean that the insurer must pay the amount claimed. The policy terms, circumstances of the event, causation, amount of loss and compliance with the claims procedure all need to be established in sequence.
We review the insured property or interest, insured risks, insured amount, deductible, policy period and applicable insurance rules.
We reconstruct the event using reports, opinions, correspondence, photographs, video, documents from public authorities and other evidence.
We analyze the specific basis of the refusal or reduction rather than arguing with the insurer in the abstract.
We determine the principal claim and any additional claims applicable to the particular situation and the client’s legal status.
The strategy is built around the specific insurance agreement and the specific insured event. There is no universal application that works the same way against every insurer.
WHAT WE DO
We review the policy terms, appendices, insurance rules, exclusions, deductibles, limits and the parties’ obligations.
We determine which facts and policy provisions the insurer relies on.
We identify the documents needed to prove the insured event, cause of damage and amount of loss.
We compare the insurer’s calculation with the documents and the cost of the damaged property, repairs or restoration works.
We prepare the application, pre-trial claim, objections, calculation and supporting documents.
We determine whether valuation, technical, commodity, construction, fire-technical or another expert examination is needed.
We formulate the legal position and support negotiations concerning payment or settlement.
We prepare procedural documents, participate in hearings and work with expert evidence and the other party’s objections.
KEY QUESTION
The name of the insurance product or policy is not enough. The agreement must be read together with the insurance rules, appendices and qualifications. Those documents define the insured risks, exclusions, liability limits, deductible and the policyholder’s duties after an event occurs.
The statement “the property is insured” does not by itself answer whether the insurer must pay in the particular situation.
What property, interest or liability was insured.
What event must occur for coverage to arise.
What circumstances the agreement excludes from coverage.
Within what limits and under what rules the payment is calculated.
INSURER’S REFUSAL
The insurer should connect the refusal to the policy terms and the actual circumstances of the event. We therefore review not only the refusal letter but also the evidence on which its conclusion is based.
A refusal needs to be broken down by legal and factual grounds. Sometimes the dispute is about interpreting the contract, sometimes about the facts, and sometimes about the amount of loss.
The evidence depends on the type of insurance and the event that occurred. The earlier the evidence is assembled, the lower the risk of losing important information.
Policy, agreement, insurance rules, appendices and amendments.
Reports, certificates, official records and materials from emergency services, police, EMERCOM and other organizations, if such documents were prepared.
Documentation of the property, damage, location of the event and consequences.
Insurer notices, applications, responses, document requests and electronic correspondence.
Estimates, invoices, specialist opinions, valuation reports and repair or restoration documents.
Contracts, delivery notes, acceptance certificates, inventory records, accounting documents and documents confirming the property’s value.
AMOUNT OF LOSS
Even when the insurer recognizes the event as insured, the dispute may continue over the cost of damage, calculation method, scope of required works, depreciation, property value or application of deductibles and limits.
We review separately:
In some cases, the dispute is not about the insured event itself but about a few figures in the calculation. Those figures may determine the amount recovered.
BUSINESS INSURANCE
For a business, an insurance dispute often concerns more than the damaged asset. An accident, fire, damage to equipment, real estate or cargo may stop production, deliveries or performance of obligations to counterparties.
Fire, flooding, utility-system accidents, damage to a building or premises.
Breakdown, accident, damage to production lines, machinery and other fixed assets.
Damage, loss or shortage during transportation.
Disputes over the existence of coverage when claims are brought against the insured person.
Inventory, machinery, equipment and other assets.
In corporate insurance, it is particularly important to compare the insurance agreement with the company’s business documents and the actual circumstances of the event.
The required procedure depends not only on the type of insurance but also on the legal status of the policyholder or beneficiary. For certain consumer financial-services disputes, the legislation provides a special pre-trial procedure involving the financial ombudsman. Commercial insurance disputes involving legal entities follow a different procedural logic.
Before preparing a lawsuit, we therefore first determine which pre-trial procedure applies to the specific dispute and which steps need to be completed for the court to consider the claim on the merits.
DO NOT DELAY
After the event, documents are created, the condition of the property is recorded, inspections are conducted and causes of damage are identified. Over time, evidence may be lost, the property repaired and the circumstances harder to reconstruct.
The earlier the future line of the dispute is understood, the easier it is to collect evidence specifically for that position.
PRACTICE
During the proceedings, SOGAZ paid RUB 2,737,500 under a personal insurance policy linked to a bank loan: RUB 2,411,252.10 to Gazprombank and RUB 326,247.90 to the two heirs. On appeal, the total penalty awarded to the heirs under Russian consumer protection law was increased to RUB 163,123.94.
View All Cases
The firm has been practicing since 2007. We handle litigation and complex legal matters for businesses in Krasnoyarsk, Moscow and other regions of Russia.
PRACTICAL APPROACH
The economics and prospects of the dispute should be assessed first: the amount claimed, quality of evidence, need for expert evidence, possible costs and the insurer’s position.
If the problem can be resolved by additional documents, a corrected calculation or a reasoned pre-trial claim, court proceedings may not be the first or only option.
If the parties’ positions fundamentally conflict, the evidence should already be prepared with future litigation in mind.
The goal is not to send the insurer as many letters as possible. The goal is to obtain a legally and economically justified result.
The agreement or policy, insurance rules, notice of the insured event, the insurer’s refusal or calculation, and the available loss documents.
We identify the basis for refusal or reduction and test it against the agreement and actual circumstances.
We determine the evidence, pre-trial route, need for valuation or expert evidence and the prospects of litigation.
We prepare the documents, communicate with the insurer and, where necessary, represent the client in court.
MANAGING PARTNER
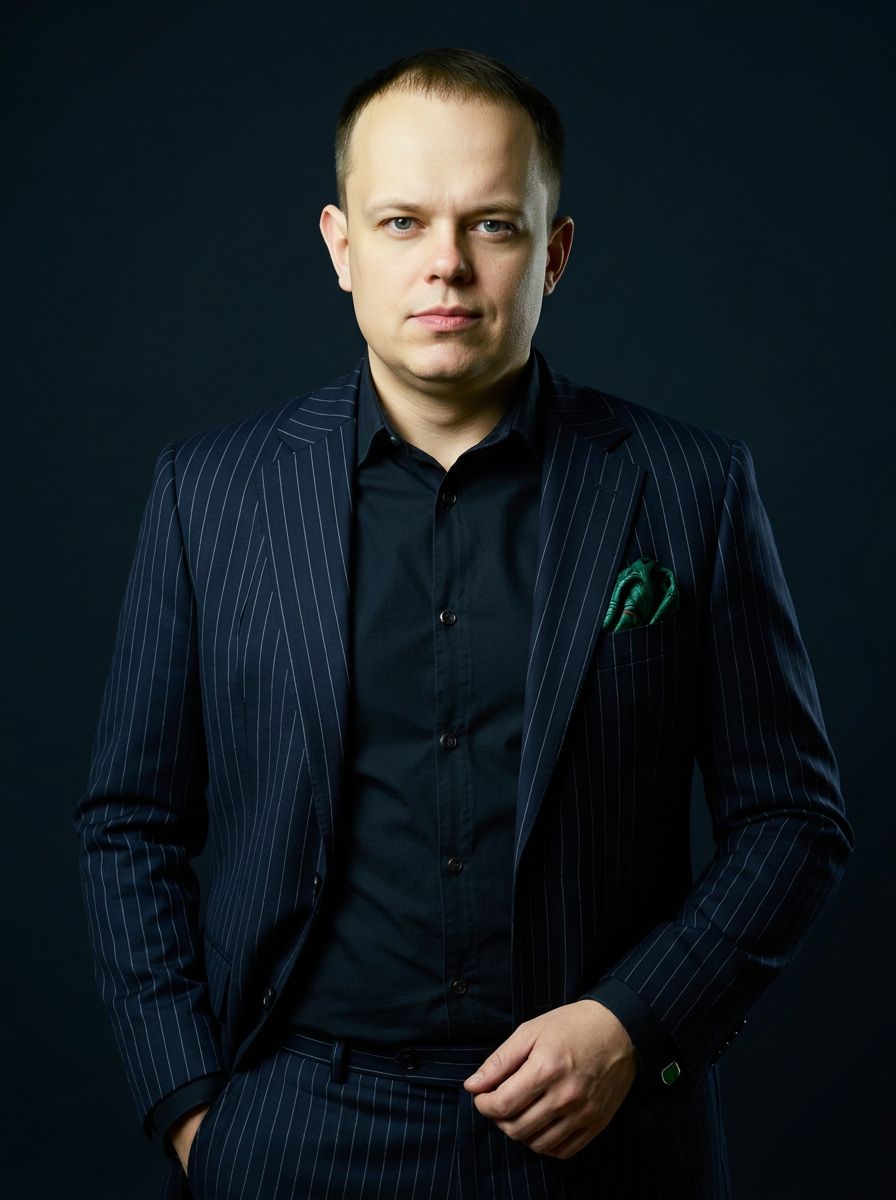
Managing Partner, Konsultant Law Firm
More than 20 years of practice in complex property and corporate disputes. Practicing insolvency practitioner.
Insurance Disputes in Practice
Practical answers for clients facing insurance claim refusals, reduced payments or disputes over compensation.
When an insurance company refuses payment, it is necessary to determine the reasons for the refusal and analyse the documents supporting the decision.
The insurance agreement, circumstances of the event and evidence supporting the policyholder’s position should be assessed.
Depending on the situation, possible steps include claims, challenging the decision or court proceedings.
The amount of insurance payment depends on the agreement terms, circumstances of the insured event and damage assessment.
If the amount is disputed, the insurer’s calculations, documents and evidence of actual damage should be analysed.
Protecting interests requires identifying the reasons for the difference between the payment and the actual claim.
Yes, an insurance company’s refusal may be challenged where legal grounds exist.
It is necessary to determine the reasons for refusal, check compliance with the agreement and prepare evidence supporting the position.
The protection method depends on the circumstances of the insured event and documents available.
The required documents depend on the type of insurance and circumstances of the dispute.
Relevant materials may include the insurance agreement, insured event documents, calculations, expert reports, correspondence and other evidence.
Before filing a claim, it is important to determine which facts need to be proven.
The need for expert assessment depends on the nature of the dispute and circumstances of the insured event.
In some cases, an expert report may help determine the amount of damage and support a party’s position.
The necessity of examination should be assessed based on the specific case.
Court recovery of insurance compensation requires preparation of a legal position and evidence.
It is necessary to establish the grounds of the claim, prove the insured event and the amount requested.
The prospects depend on the agreement terms and circumstances of the case.
Insurance disputes require analysis of agreements, documents, event circumstances and the insurer’s position.
A lawyer helps assess prospects, prepare documents and choose a protection strategy.
The approach depends on the type of insurance and specific circumstances.
CASE REVIEW
Briefly describe what happened and what the insurer said. If documents are already available, prepare the policy, insurance rules, refusal or payment calculation — they will be needed to analyze the insurer’s position.